October 05, 2026
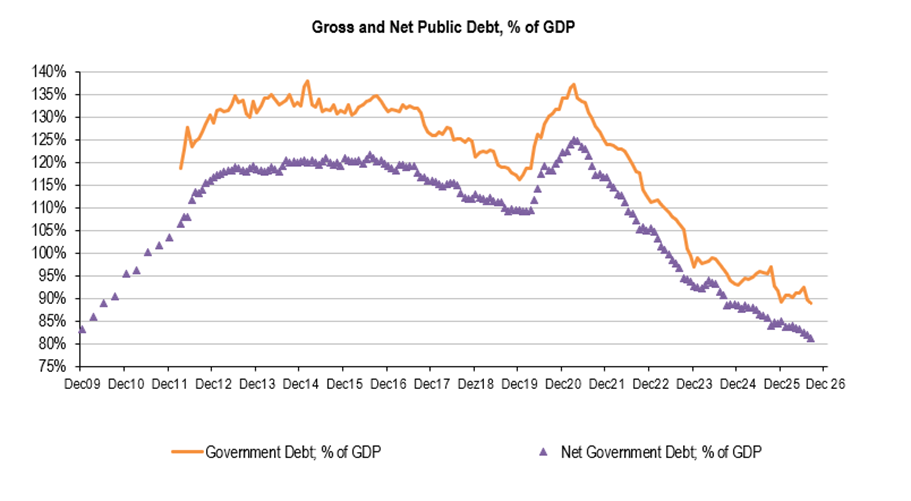
Quick Comment: Government Debt, in August, before deposits of public Administration, -104bpYoY/-20bpMoM to €285.6Bn, 89.0% of GDP (LTM), and after deposits €260.6Bn, +42bpYoY/-57bpMoM. Debt before deposits outperformed, went down 20bp MoM or roughly €558Mn. The positive performance should continue until year end, mainly due to lower deposits, as budget execution points to a small surplus. So, debt Government’s initial target of 87,5% of GDP at YE26, should be reached or surpassed.
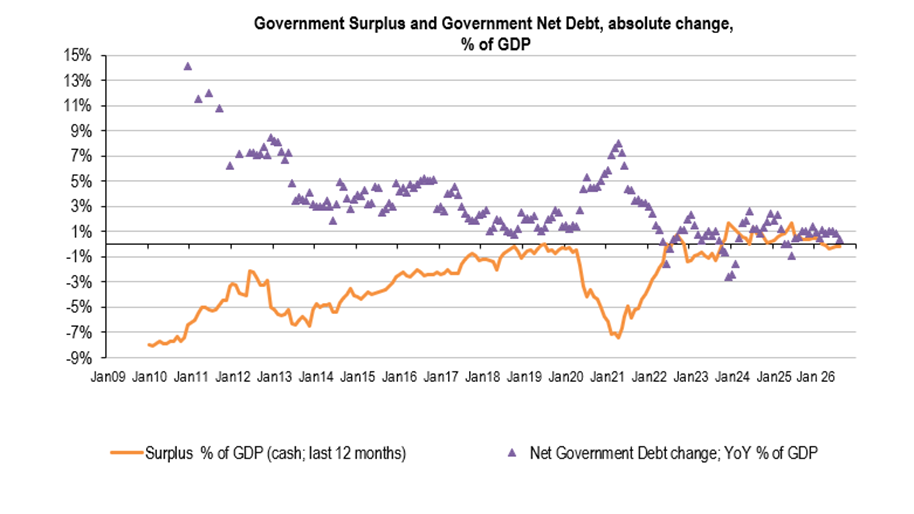
Meanwhile, budget execution remains under pressure, August’s surplus €249Mn YtD vs. a surplus in August25 of €2,048.6Mn; however, excluding several non-recurrent payments made by the SNS since March 2026 (€1,426.5Mn) , the surplus would be €1,675Mn, still below the surplus in 2025. Revenues are growing at 7.9%YtD vs. Expenditures, +10.4%YtD or adjusted by non-recurrent payments, 8.6%YtD. Even so, taking in consideration the past performance, namely the last two years, the deficit on a cash basis at yearend should be below €1Bn, while excluding the non-recurrent payments €1.4Bn, it means a small surplus on public accounts, in line with government forecast.
(reading time: 4 mins)
The Bank of Portugal released August’s Government debt data, by the end of lats week (we were just able to comment today, sorry for any inconvenience).
The main highlights are the following:
1 – Gross Government debt (Maastricht definition): €285,627Mn; -104bpYoY/-20bpMoM and 89.0% of GDP last 12months (LTM) vs. 12MMA (12 Months Moving Average): 91.3%/3MMA: 90.3% (initial target YE26: 87.5%);
2 – Net Government debt (after the deposits of Public Administration; Maastricht definition): €260,578Mn +43bpYoY/-57bp MoM (-€1 158Mn YtD) and 81.2% of nominal GDP vs. 12MMA: 83.6%/3MMA: 81.9%.
Separately, the finance minister released on the last day of September at evening, August’s budget execution. We would highlight the following:
1 – Surplus: €249Mn YtD (January till August); -€1,799Mn vs. 2025 (Jan till August);
2 – Deficit in percentage of GDP, on a cash basis, last 12 months: -0.16% vs. 12MMA: +0.10%/3MMA: -0.23%;
3 – Effective Revenues: +7.9%YtD vs. 12MMA: 7.7%/3MMA: 12.7% (initial budget target 2026: +8.6%);
Direct Taxes: +3.6%YtD vs. budget: +2.0% (IRS: +7.1%YtD/IRC: -5.7%);
Indirect Taxes: +6.1%YtD vs. budget: +4.9% (VAT: +8.8%YtD/“Tax on oil…”: -3.9%)
Contributions (mainly social security contributions, CGA…): +6.8%YtD vs. budget: +5% (12MMA: 7.3%/3MMA: 6.3%);
Non-Tax and Non-Contributory Revenues (dividends, transfers…): +25.9%YtD vs. budget +30.5%.
4 - Effective Expenditure +10.4%YtD vs. 12MMA: 9.99%/3MMA: 11.54% (initial budget: +10.5%);
Employees: +5.5%YtD vs. budget, 4.8%;
Purchase of Goods and Services: +18.3%YtD vs. budget: +2.3% (influenced by the non-recurrent payments to the SNS, €1,426.5Mn, since March/26);
Interest and Other Charges: +10.4%YtD vs. budget +5.1%;
Current Transfers (mainly, pensions and social support): +5.3%YtD vs. budget: 6.6% (Pensions, unemployment benefits…: +3.9%YtD and “CGA” (civil servant pensions): +2.8%);
Others (subsidies, Investment…): +34.1% vs. budget: 47.7%.
Comment: Public debt, Maastricht definition, in August, outperformed -€558Mn MoM; to €285.6Bn, roughly 89% of GDP, while after Deposits, net debt also outperformed MoM at €260.6Bn, even so roughly €1.1BnYoY, however -€1.1BnYtD, vs. a surplus on a cash basis of roughly €249MnYtD. We believe Deposits will continue to go down, so Debt, at YE26, Maastricht definition will be below Governments initial target 87.5% of GDP.
Concerning, August’s budget execution, the surplus is now €249Mn YtD -€1,799Mn than in August 2025; partially explained by several non-recurrent payments, March to August totalling €1,426.5Mn (payments made by the SNS (National Healthcare System) and justifies the “Purchase of Goods & Services” performance, +18.3%YtD vs. budget +2.3%. Adjusted by the extraordinary payment the surplus would be €1,675Mn, still below the surplus in 2025 (until August): +€2,048.6Mn.
All in all, the budget execution remains under pressure, mainly because Effective Revenues +7.9%YtD, below target (+8.6%) and below Expenditures, +10.4%YtD or excluding the non-recurrent payment, €1,426.5Mn; +8.6%YtD. Revenues, +7.9%YTD, o/w Direct Taxes: +3.6%; Indirect Taxes: +6.1%, Social Security Contributions: +6.8%, while expenditures +10.4%YtD, o/w Employees: 5.5%YtD; Interest: +10.4%YtD and “Current Transfers” +5.3%. Nevertheless, in 2025 and 2024, the deficit on a cash basis, in the last four months of the year was, €751Mn and €112Mn, respectively, so seem fair to assume a deficit. on a cash basis in 2026, below €1Bn, meanwhile if we exclude, the non-recurrent payments, €1.4Bn; mentioned before (already booked regarding public debt), we should expect a small surplus, in line with government forecasts.
Source: Bank of Portugal, INE, AS Independent Research
António Seladas, CFA
Back