September 02, 2026
(reading time: 4 mins)
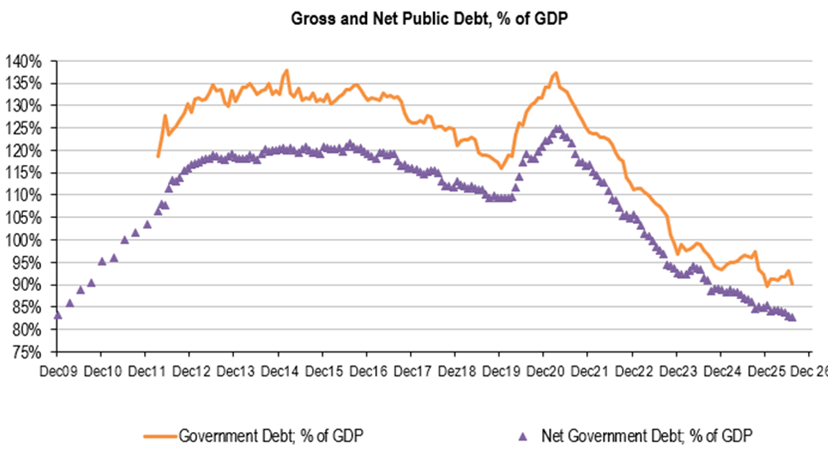
Quick Comment: Government Debt, in July, before deposits of public Administration, -63bpYoY/-257bpMoM; €286.34Bn, 90.3% of GDP (LTM), and after deposits €262.2Bn, +113bpYoY/-8bpMoM. Debt before deposits outperformed, went down 257bp MoM or roughly €7.5Bn; mainly due to lower deposits. The trend of lower deposits should continue until the year end, as Deposits currently at €24Bn should finish the year at €15Bn or below, so public debt, Maastricht definition, should finish the year at government’s initial target, 87.5% of GDP or below.
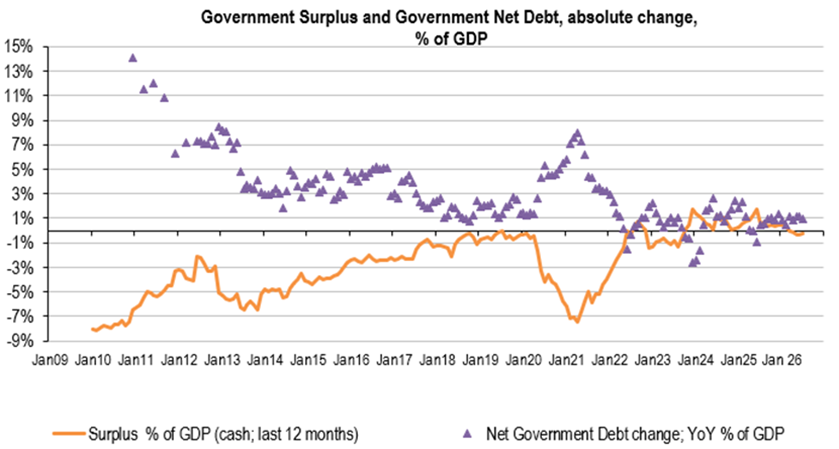
Meanwhile, budget execution remains under pressure, July’s surplus €281.7Mn YtD vs. a surplus in July25 of €2,321Mn YtD; excluding several non-recurrent payments made by the SNS since March 2026 (€1,426Mn) , the surplus would be €1,708Mn, still below the surplus in 2025. Nevertheless, revenues are growing at 7.4%YtD vs. Expenditures, +10.6%YtD or adjusted by non-recurrent payments, 8.5%YtD. Finally, structural expenditures, continue to grow above 5%, namely, Employees: 6.2%YtD, Interest: +10.2%YtD and Current Transfers: +5.9%, what could be a problem in an economic downturn…
The Bank of Portugal released July’s Government debt data, yesterday (we were just able to comment today, sorry for any inconvenience).
The main highlights are the following:
1 – Gross Government debt (Maastricht definition): €286,340Mn; -63bpYoY/-257bpMoM and 90.3% of GDP last 12months (LTM) vs. 12MMA (12 Months Moving Average): 92.4%/3MMA: 91.7% (initial target YE26: 87.5%);
2 – Net Government debt (after the deposits of Public Administration; Maastricht definition): €262,244Mn +113bpYoY/-8bp MoM (+€522Mn YtD) and 82.7% of nominal GDP vs. 12MMA: 84.4%/3MMA: 83.2%.
Separately, the finance minister released yesterday before evening, July’s budget execution. We would highlight the following:
1 – Surplus: €281.7Mn YtD (January till July); -€2,040Mn vs. 2025 (Jan till July);
2 – Deficit in percentage of GDP, on a cash basis, last 12 months: -0.23% vs. 12MMA: +0.16%/3MMA: -0.29%;
3 – Effective Revenues: +7.4%YtD vs. 12MMA: 7.9%/3MMA: 8.3% (initial budget target 2026: +8.6%);
Direct Taxes: +3.4%YtD vs. budget: +2.0% (IRS: +5.9%YtD/IRC: -2.1%);
Indirect Taxes: +5.0%YtD vs. budget: +4.9% (VAT: +6.8%YtD/“Tax on oil…”: -2.3%)
Contributions (mainly social security contributions, CGA…): +6.7%YtD vs. budget: +5% (12MMA: 7.3%/3MMA: 5.6%);
Non-Tax and Non-Contributory Revenues (dividends, transfers…): +18.7%YtD vs. budget +30.5%.
4 - Effective Expenditure +10.6%YtD vs. 12MMA: 10.2%/3MMA: 10.6% (initial budget: +10.5%);
Employees: +6.2%YtD vs. budget, 4.8%;
Purchase of Goods and Services: +18.9%YtD vs. budget: +2.3% (influenced by the non-recurrent payments to the SNS, €1,426Mn, since March/26);
Interest and Other Charges: +10.2%YtD vs. budget +5.1%;
Current Transfers (mainly, pensions and social support): +5.9%YtD vs. budget: 6.6% (Pensions, unemployment benefits…: +4.3%YtD and “CGA” (civil servant pensions): +4.3%);
Others (subsidies, Investment…): +30.9% vs. budget: 47.7%.
Comment: Public debt, Maastricht definition, in July, outperformed -€7,553Mn MoM; to €286.3Bn, roughly 90.3% of GDP, while after Deposits, net debt was almost flat MoM at €262.2Bn, roughly +€522MoM above the level at YE25, compares with the budget surplus on a cash basis €282MnYtD. Public debt strong swing MoM is mainly explained by the strong reduction of Deposits -€7.3BnMoM to €24Bn, in line with 12MMA. Nevertheless, we believe Deposits will continue to come down until the year end and it should be around €15Bn or lower by December 2026 (since 2021, deposits at yearend were around €15Bn or below), consequently public debt by the yearend, Maastricht definition, should be at Government initial target, 87.5% of GDP or below.
Concerning, July’s budget execution, the surplus is now €281.7Mn YtD -€2,040Mn than in July 2025; partially explained by several non-recurrent payments, March to July totalling €1,426.4Mn (made by the SNS (National Healthcare System) and justifies the “Purchase of Goods & Services” performance, +18.9%YtD vs. budget +2.3%. Adjusted by the extraordinary payment the surplus would be €1,708Mn, still below the surplus in 2025 (until July): +€2,322Mn.
All in all, the budget execution remains under pressure, mainly because Effective Revenues +7.4%YtD, below target (+8.6%) and below Expenditures, +10.6%YtD or excluding the non-recurrent payment, €1,426Mn; +8.5%YtD. Revenues, +7.4%YTD, o/w Direct Taxes: +3.4%; Indirect Taxes: +5.0%, Social Security Contributions: +6.7%, while expenditures +10.6%YtD, o/w Employees: 6.2%YtD; Interest: +10.2%YtD and “Current Transfers” +5.9%. Meanwhile, Revenues from Social Security Contributions are slowing down, three months in a row growing below 6.5%. In general, structural expenditures continue to grow above 5% or higher,, which is a reason for concern, namely in an economic downturn.
Source: Bank of Portugal, INE, AS Independent Research
António Seladas, CFA
Back